Planning for your financial future is one of the most crucial steps that people take nowadays. While looking towards the future, you may find yourself asking, “How can I create a safety net to ensure that my living expenses continue to be paid during my retirement years?” In the midst of contemplating, you may also realize that you have certain short-term financial needs that arise every few years.
While looking at insurance and investment plans in India, you may stumble across the terms a money back policy and a retirement plan. Although both policies provide life coverage and financial returns, the two policies have entirely different objectives. Depending on whether you wish to provide yourself with a stream of cash flow during your working years or during your retirement age will decide which policy is most suitable for you. In this article, let’s dissect the differences between the two financial products.
What is a Money Back Policy?
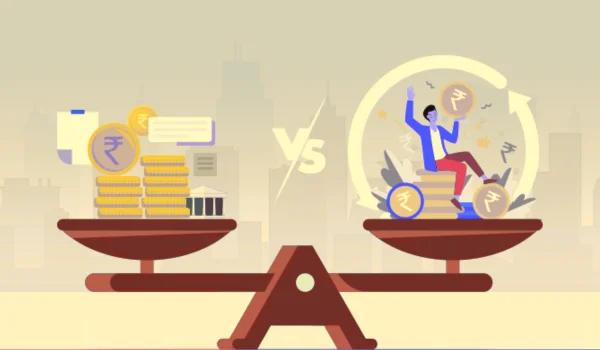
A money back policy is a type of life insurance that provides periodic payouts to its holders. Instead of waiting until the end of the policy to receive your money, money back policies periodically pay out a certain percentage of the money.
For instance, if you invest in a twenty-year money back policy, you may receive payouts every five years. At the end of the policy, if you are still alive, you receive the balance along with the declared bonuses. In the case that the policyholder had died while the policy was active, the nominee will receive the entire sum assured despite having received interval payouts.
Overview of Features
- Guaranteed Liquidity: You receive cash payouts at scheduled years to cater to your needs, such as home repairs, children’s education, and vacations.
- Life Coverage: Provides your loved ones with financial assistance for the duration of the policy.
- Minimal Risk: As no market risk is involved, money-back policies are ideal for individuals who seek to safeguard their investments.
What is a Retirement Plan?
When searching for the best retirement plan in India, you may note that a retirement plan is a financial product that allows you to set aside a substantial amount of money meant for your golden years. A retirement plan (also known as a pension plan or annuity plan) consists of two phases.
- Accumulation Phase: You periodically pay the premium while you are employed to form a retirement corpus.
- Distribution Phase: Once you attain the age of superannuation (typically at the age of 60), you are eligible to withdraw a portion of your retirement corpus as a lump sum. The remaining amount of the retirement corpus is converted to an annuity plan where you receive a monthly or yearly pension for the remainder of your life.
Overview of Features
- Long-Term Wealth Creation: Designed to help you accumulate substantial wealth to combat inflation over the decades.
- Post-Retirement Income: Ensures that you don’t outlive your savings (subject to the annuity plan selected).
- Disciplined Savings: With your retirement funds being inaccessible until you near retirement age, the likelihood of you misusing the money decreases significantly.
Overview of Tax Benefits
Under the provisions of the New Income Tax Act, 2025, here are the tax benefits pertaining to the insurance products:
Tax Deductions on Premiums Paid
The premiums paid towards eligible life insurance plans (that include a money back policy or pension accumulation plan) are eligible for tax deductions up to ₹1.5 lakh under Section 123 of the New Income Tax Act, 2025 (subject to the conditions and income tax slab of the policy).
Taxability of Payouts and Maturity Amounts
Money Back Payouts & Maturity: Payouts and maturity proceeds from a life insurance policy may be exempt from tax under Section 10(10D) of the Income Tax Act, provided the annual premium does not exceed prescribed percentages of the sum assured or overall limits defined under current tax regulations.
Retirement Annuity Payouts
Upon the maturation of your retirement plan, any lump sum withdrawal may enjoy partial exemption depending on the specific product structure (e.g., NPS or insurance pension rules under Schedule II). Nonetheless, regular annuity (pension) payments received post-retirement are considered income and are taxable at your applicable income tax slab rates under Section 17(1)(ii).
Note: Tax laws are subject to change. Tax benefits may vary depending on individual circumstances, the tax regime selected, and the terms of the insurer. It is always advisable to consult a qualified tax advisor before making any financial decisions.
Which Policy Fits Your Financial Objectives?
Both policies can’t be compared on a relative level since both have varying objectives.
Select a Money Back Policy if:
- You have set aside financial milestones for your family members in the next 5, 10, or 15 years.
- You want one policy that can provide periodic cash flow as well as life coverage.
- You want guaranteed and stable returns without the risks of market fluctuations.
Select a Retirement Plan if:
- You wish to create a financial stream of income to provide yourself a pension during your golden years.
- You wish to avoid the temptation of misusing your retirement funds.
- You want to take advantage of compounding your money for 20 to 30 years to counter inflation.
Can You Have Both Policies?
Of course! Some individuals tend to set aside both financial products. A policyholder can use a money back policy to cater to their short-term financial needs while utilizing the best retirement plan in India to provide themselves with a pension fund for their post-retirement years.
Before making any purchases, compare features, claim settlement records, eligibility, and policy details of all the policies that you wish to invest in. The premium rates, riders, and maturity terms may greatly vary between insurance providers, and the conditions are subject to individual underwriting.

Leave a Reply